Microfinance is an important part of India’s financial-inclusion system. It provides small, usually collateral-free loans to low-income households that may not qualify for conventional bank credit. These loans commonly support tailoring, food businesses, livestock, farming, small shops and other income-generating activities. Women form a large majority of microfinance borrowers in India.
The industry faced repayment pressure and slower lending during 2024 and 2025. By March 2026, however, the sector recorded its first quarter-on-quarter portfolio growth in several quarters, indicating an early recovery. Responsible lending, transparent pricing and careful checks on multiple borrowing have now become more important than rapid loan growth. Considering loan portfolio, borrower reach, branch network, financial strength, responsible-lending practices and long-term contribution to financial inclusion, let’s check out the top 10 microfinance companies in India in 2026. The list includes dedicated NBFC-MFIs and banks with substantial microfinance operations.
1. CreditAccess Grameen
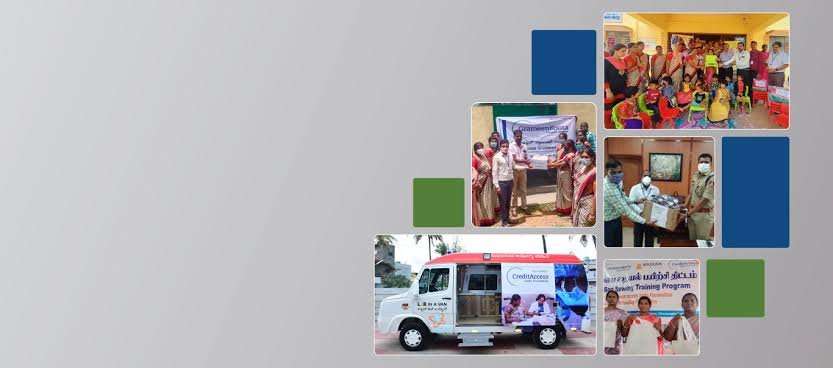
CreditAccess Grameen is India’s largest dedicated NBFC-MFI and the strongest overall name in the sector. Its assets under management reached ₹29,590 crore in FY2026, while its network expanded to more than 2,200 branches.
The company mainly serves women through group loans but is gradually adding retail-finance products for existing customers. Its scale, rural knowledge, disciplined underwriting and recovery during FY2026 place it first on this list.
2. Bandhan Bank
Bandhan began as a microfinance organisation in 2001 and became a universal bank in 2015. Although it now provides complete banking services, microloans remain central to its financial-inclusion business.
Its major advantage is the ability to provide borrowers with savings accounts, insurance, remittances and larger business loans as they progress. Bandhan’s extensive eastern and north-eastern presence, large customer base and deposit-funded model give it a distinctive position.
3. Ujjivan Small Finance Bank
Ujjivan started its journey as a microfinance institution in 2005 before becoming a small finance bank. It continues to maintain a large microbanking operation while expanding into housing, vehicle, MSME and other secured loans.
The bank’s total loan book crossed ₹40,000 crore in FY2026. A broad branch network, multilingual customer service, deposit facilities and experience serving urban and semi-urban borrowers make Ujjivan one of India’s leading inclusive-finance institutions.
4. Svatantra Microfin
Founded by Ananya Birla, Svatantra Microfin has grown into one of India’s largest dedicated microfinance platforms. Its acquisition and eventual amalgamation with Chaitanya India Fin Credit considerably expanded its borrower and branch network.
The company is known for technology-supported field operations, cashless disbursement and loans designed for rural women entrepreneurs. Strong institutional backing and nationwide expansion make Svatantra an important long-term competitor to listed MFI leaders.
5. Satin Creditcare Network
Satin Creditcare has more than 35 years of experience in lending to underserved households and small entrepreneurs. Its consolidated assets under management reached approximately ₹15,174 crore in FY2026.
The group serves over three million customers and has one of the industry’s widest geographic footprints. Apart from group-based microfinance, it operates in MSME lending, housing finance and business-correspondent services, reducing its dependence on a single loan category.
6. Muthoot Microfin
Muthoot Microfin is a major member of the Muthoot Pappachan Group and one of India’s largest listed NBFC-MFIs. At the end of FY2026, it had an AUM of approximately ₹14,006 crore, 3.27 million active customers and 1,670 branches.
The company mainly finances women through joint-liability groups. Its established brand, diversified state presence, improving collection efficiency and growing individual-loan portfolio strengthen its industry position.
7. Annapurna Finance
Bhubaneswar-based Annapurna Finance is one of eastern India’s most successful financial-inclusion companies. It grew from a local development organisation into a nationwide NBFC-MFI, reporting AUM of approximately ₹11,535 crore in FY2026.
Annapurna provides group loans, MSME finance, housing-improvement loans and other livelihood-focused products. Its knowledge of rural markets, strong presence in underbanked regions and focus on women entrepreneurs make it particularly important for eastern and central India.
8. Arohan Financial Services
Arohan Financial Services has operated in microfinance since 2006 and is especially strong in eastern, north-eastern and underserved Indian markets. It served around two million borrowers across 17 states with an AUM of roughly ₹6,000 crore during FY2026.
Arohan provides income-generating loans and other financial products mainly to women. Its long operating history, rural distribution and improving asset-quality indicators support its place among India’s leading MFIs.
9. Fusion Finance
Fusion Finance remains an important nationwide microfinance lender despite passing through a difficult credit cycle. Its portfolio had reduced to approximately ₹7,000 crore, after which the company completed an ₹800-crore rights issue to strengthen its capital base.
Fusion primarily lends to women running small livelihood activities and possesses a large multi-state network. Improved underwriting and successful portfolio rebuilding will determine how strongly it moves up this list in future.
10. Asirvad Micro Finance
Asirvad Micro Finance, a subsidiary of Manappuram Finance, had an AUM of ₹6,793 crore at the end of FY2026. It served approximately 29.4 lakh borrowers through 1,765 branches across 26 states and union territories.
Its principal customers are economically disadvantaged women borrowing through joint-liability groups. Strong promoter backing and broad reach are major advantages, although maintaining asset quality after the recent sector-wide stress remains important.
Frequently Asked Questions
Q1. Which microfinance company offers the lowest interest rate?
A: Rates change according to funding costs, location, loan type and borrower profile. Compare the annual interest rate, processing fee, insurance charge, repayment frequency and total amount payable—not merely the advertised monthly instalment.
Q2. Is collateral required for a genuine microfinance loan?
A: No. Under RBI rules, a microfinance loan is collateral-free and intended for a household with annual income up to ₹3 lakh. An agent should not demand gold, land documents or another asset as security.
Q3. How can borrowers confirm that a field agent is genuine?
A: Verify the agent’s identity through the lender’s official branch or customer-care number. Obtain a loan card and receipt for every payment. Never transfer money to an agent’s personal UPI account or share an OTP, PIN or banking password.
Q4. Can a person borrow from several microfinance lenders?
A: Lenders check credit-bureau records and household repayment capacity before sanctioning loans. Multiple loans can cause over-indebtedness and rejection of a new application. Borrowers should disclose every existing loan and avoid borrowing simply to repay another lender.
Q5. Where can borrowers complain about harassment or incorrect charges?
A: First complain to the lender’s grievance officer using the details printed on the loan card or fact sheet. If a regulated bank or NBFC does not resolve the matter satisfactorily, a complaint can be filed through the